The digital asset ecosystem has evolved dramatically over recent years. What was once considered by many to be an unregulated financial frontier now operates under an aggressive, globally coordinated tax enforcement framework. Tax authorities worldwide deploy advanced on-chain analytics, automated data-sharing protocols, and statutory reporting regimes to track blockchain transactions down to individual wallet addresses.
Navigating the tax rules in 2026 is critical to prevent severe administrative penalties, bank account freezes, and unexpected surcharges. This guide breaks down the core legal foundations you need to file your crypto taxes accurately while leveraging compliant optimization strategies.
1. The Global Regulatory Framework: DAC8, MiCA, and CARF
To understand digital asset taxation in 2026, you must first assess the international compliance infrastructure:
┌─────────────────┐       ┌─────────────────┐       ┌─────────────────┐
│    EU / MiCA    │       │    EU / DAC8    │       │    OECD CARF    │
│ Strict CASP     │ ────► │ Automated user  │ ────► │ Cross-border    │
│ licensing & KYC │       │ balance reports │       │ data exchange   │
└─────────────────┘       └─────────────────┘       └─────────────────┘
- Markets in Crypto-Assets (MiCA): Enforced across the European Union, MiCA requires all Crypto-Asset Service Providers (CASPs) to maintain strict Know-Your-Customer (KYC) records, formal audits, and regulatory registration.
- The DAC8 Directive: This EU administrative cooperation directive mandates that both domestic and foreign exchanges serving European residents automatically report transaction histories, year-end balances, and taxpayer identities directly to local revenue agencies.
- The OECD’s Crypto-Asset Reporting Framework (CARF): Adopted across dozens of non-EU jurisdictions (including the United States, the UK, Canada, and Japan), CARF enables multilateral tax information sharing, mirroring the traditional Common Reporting Standard (CRS) used in banking.
2. Taxable Events vs. Non-Taxable Transactions
A frequent misconception among investors is assuming that taxes apply only when «cashing out» to fiat currency (EUR, USD). Under tax law, virtually every trade constitutes an independent realization event.
A. Crypto-to-Crypto Swaps (Like-Kind Exchanges)
Trading Bitcoin (BTC) for Ethereum (ETH) or swapping volatile tokens for stablecoins (USDT, USDC) is treated as a property barter/disposal. Even if fiat currency never touches your bank account, you must calculate capital gains or losses by comparing the fiat fair market value (FMV) of Asset A at the moment of disposal against its original acquisition cost.
B. Crypto-to-Fiat Liquidations
Selling digital assets for fiat currency is a standard capital disposal. The taxable gain or loss is determined as:
Taxable Gain/Loss = Gross Sale Proceeds -Disposal Fees – Acquisition Cost + Purchase Fees
C. Purchasing Goods and Services with Crypto
Using crypto directly or via crypto-linked debit cards (such as Binance or Coinbase Card) to settle payments incurs a disposal event. Delivering crypto as payment triggers a capital gains tax liability on any asset appreciation that occurred between the initial purchase date and the transaction date.
3. Cost-Basis Accounting: The FIFO Mandate
When acquiring the same digital asset across different dates and price points, tax frameworks (including Article 37.2 of Spain’s IRPF Law and international counterparts) generally mandate the First In, First Out (FIFO) accounting method:
Purchase 1: 1 BTC @ $20,000  ──┐
Purchase 2: 1 BTC @ $40,000    │──► Sale of 1 BTC @ $50,000
                               │    Assigned Cost Basis: $20,000 (Purchase 1)
                               └──► Realized Capital Gain: $30,000
FIFO assumes the earliest acquired units are the first ones liquidated. Due to the complexity of tracking dozens of swaps across decentralized and centralized protocols, using dedicated crypto tax accounting software (such as Koinly, CoinTracking, or TokenTax) is virtually essential.
4. Savings Tax Brackets for Capital Gains (Spain Benchmark)
In dual-income tax regimes (like Spain), capital gains realized from crypto disposals qualify as savings income (base imponible del ahorro), avoiding higher marginal labor tax rates in favor of a progressive scale:
| Net Capital Gain Bracket | Applicable Tax Rate |
| Up to $6,000 | 19% |
| $6,000 to $50,000 | 21% |
| $50,000 to ~$200,000 | 23% |
| $200,000 to $300,000 | 27% |
| Exceeding $300,000 | 28% |
(Note: Rates reflect the standard statutory savings income brackets in Spain. Regional variations or wealth surcharges may apply based on fiscal residency).
5. Tax Treatment of Complex Transactions: Staking, Airdrops & DeFi
Web3 mechanics require specific tax classifications depending on how rewards are earned:
- Staking & Liquidity Farming: Classified as investment income (rendimientos del capital mobiliario). Rewards are taxed based on their fiat market value at the exact timestamp they become accessible in your wallet. When later sold, that declared value serves as the updated acquisition cost basis.
- Airdrops: Treated as ordinary income or general capital gains not derived from asset transfers (ganancia patrimonial en la base general). They are taxed alongside employment income at general progressive rates, using the fair market value upon receipt.
- DeFi Lending: Yield generated from lending protocols (e.g., Aave, Compound) is taxed as investment income within the savings tax bracket (19% to 28%).
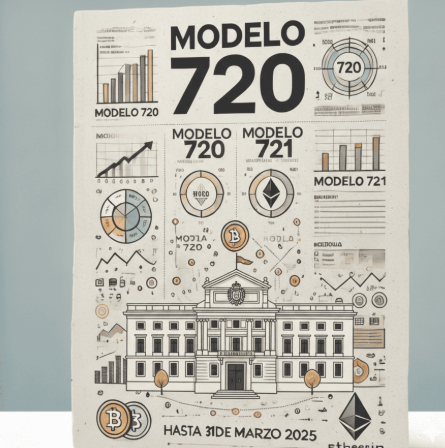
6. Mandatory Information Filings: Forms 172, 173, and 721 (Spain)
Beyond settlement of annual gains, statutory disclosure forms monitor holdings:
- Form 172 (Domestic Balances): Submitted directly by Spanish-registered exchanges, reporting user identities and year-end token balances.
- Form 173 (Domestic Operations): Submitted by local platforms detailing transaction volumes, transfers, and customer counterparties.
- Form 721 (Foreign Crypto Holdings): Submitted by individual taxpayers holding digital assets in non-Spanish custodial platforms (e.g., Kraken, Binance, Coinbase) when total foreign balances exceed €50,000 as of December 31st.
Self-Custody Wallets (Ledger, Trezor): Under current tax rulings, non-custodial hardware wallets where the user holds exclusive custody of private keys within national territory are generally exempt from Form 721. However, they remain subject to Wealth Tax (Impuesto sobre el Patrimonio) if overall net worth crosses regional exemption thresholds.
7. Legal Tax Optimization Strategies
Tax planning allows investors to reduce their effective liabilities through compliant measures:
- Tax-Loss Harvesting: Realizing losses on underperforming tokens before December 31st to offset capital gains generated throughout the fiscal year.
- Loss Carryforward Provisions: Unused net capital losses can offset up to 25% of investment income (e.g., staking yields) in the current year, with any remaining balance carried forward for up to 4 consecutive tax years.
- Long-Term Holding: Unrealized gains generate zero immediate tax liability. Deferring transactions enables capital compounding without annual tax drag.
- Relocation of Tax Residency: High-net-worth investors frequently establish bona fide residency in crypto-friendly jurisdictions (e.g., Andorra, UAE, Switzerland). Compliance requires satisfying physical presence tests (>183 days) and severing primary economic ties to mitigate exit tax and audit challenges.
Managing crypto asset compliance requires proactive accounting and structural clarity. Tracking on-chain operations with audited tooling and consulting qualified tax professionals ensures optimal capital preservation while maintaining full legal compliance.
Disclaimer: This article is for informational and educational purposes only and does not constitute personalized legal, tax, or financial advice. Tax laws vary by jurisdiction and are subject to dynamic regulatory updates. Consult a certified tax advisor in your jurisdiction before executing financial transactions or filing returns.